
This is how you can get more than NOK 100,000 more in pension
Especially if you are young, a simple move can now secure you more money when you retire. Avoid your pension being eaten up by high fees!
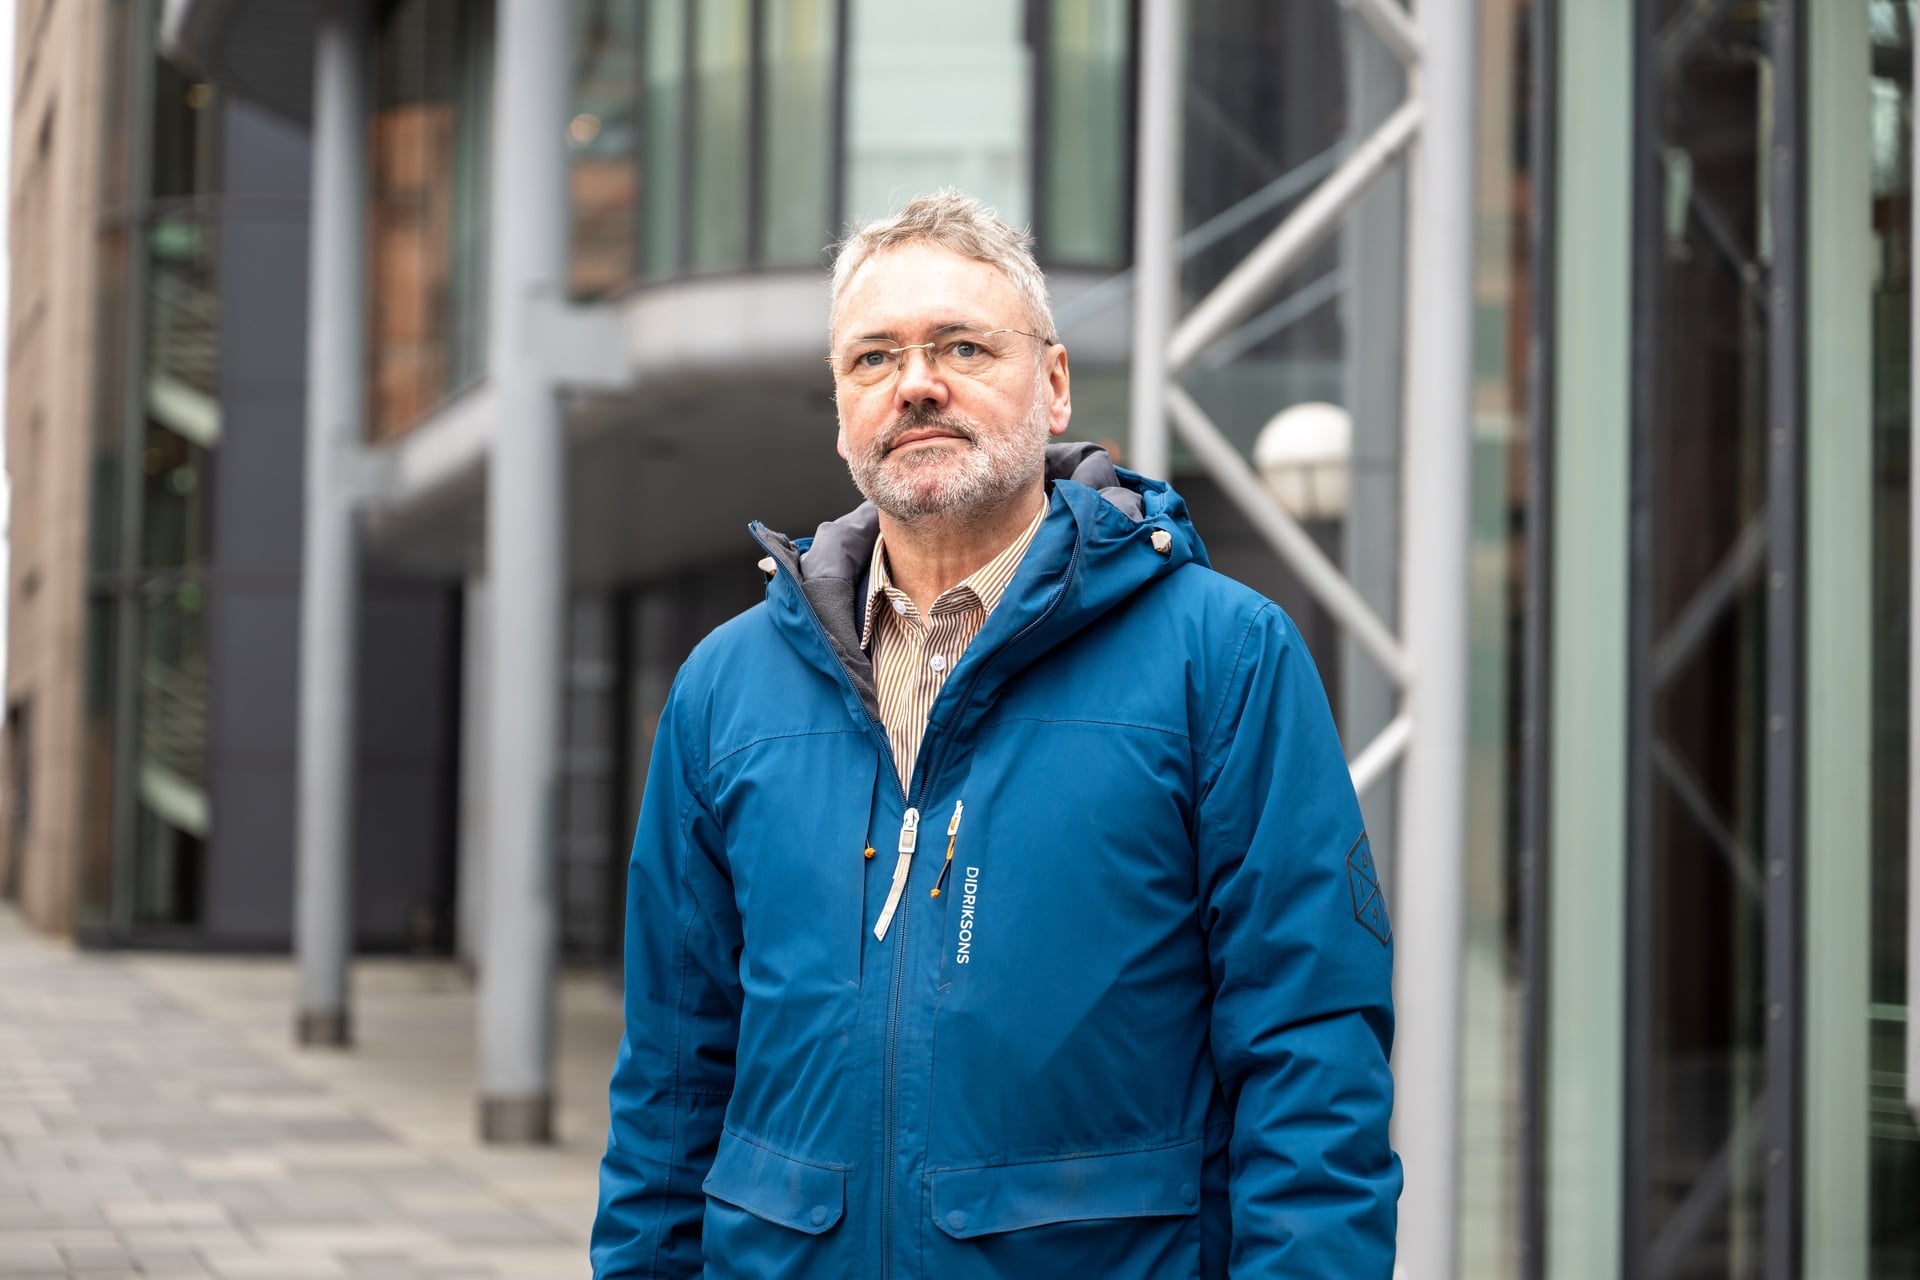
- Check your retirement account today And choose a provider that does not eat up your pension. This is what Knut Aarbakke, special adviser at NITO, says.
He thinks mAnge thinks that pension is something you should worry about later, not now. - Such a thought can cost you dearly! The younger you are when you get into this, the better it is, he says.
It is not only how good the pension scheme is that has an impact on what you receive in pension:
– Which pension provider you have; and how much you pay in fees and management costs for pension accrual, has a major impact on how much you are actually left with as a pensioner. You are free to choose which provider will manage your pension, and it will be beneficial if you switch to one with lower costs. The earlier you take action, the greater the gain can be.
Knut Aarbakke, Special Adviser at NITO
Can I transfer my pension?
Everyone who has or has had a job in the private sector gets a pension account with money to be withdrawn when you retire. But then you may have to take action early! This perspective over time has something to say.
Aarbakke believes that the pension providers charge well for managing the pension money.
He points out that many people do not know that the costs are deducted directly from your pension money. Thus, it is not noticeable in the same way as a regular bill. The result is that many people are stuck in expensive schemes without being aware of it.
The separate pension account scheme (EPK) has made it easier to move your pension: " You can always choose yourown provider. And that choice can have a big impact over time," says Aarbakke.
Defined-contribution pension, pension capital certificate and own pension account
- A defined contribution pension when you are in an employment relationship is often called a "separate pension account" (EPK). It is a pension account that your employer puts money into every month for you. How much depends on how good the scheme is; between two and seven percent of salary.
- The employer also covers the management costs of the pension provider. After the introduction of EPK, you can choose to invest the money with another pension provider. And you will receive more pension if you choose a pension provider with lower costs.
- Pension capital certificates are money from defined contribution pensions with previous employers, and are also in this account, but you cover the costs of this part of the pension money yourself, at the price the employer has agreed with the pension provider. If you do not have an employer with a defined contribution pension, you will normally pay significantly higher management costs than what applies to employers. In such cases, it will very often be worthwhile to transfer the pension.
- If you are a member of a trade union, the offer through it is often better than what you get through your employer. Your employer will have to pay the same amount for fees and management costs even if you are able to move your account to a cheaper provider.
Examples
NITO member first saved 15,000, then much, much more
A NITO member had a pension capital certificate with active management of his or her pension accrual, at a price of 1.15 per cent of the capital.
Through NITO's agreement with Nordea Liv, the corresponding management could be given at 0.39 per cent. With a capital of NOK two million, this amounted to NOK 15,000 saved per year. The member chose to change his pension solution and at the same time switched to index management, which made the savings even greater.
– 15. 000 kroner is in itself a remarkably large sum," says Aarbakke. "But when you multiply this by all the years you are in work and think that the stock market also provides a good return on your money, the sum can be many hundreds of thousands.
NITO student who can save a lot over many years
A hypothetical example for a NITO student who has a pension capital certificate of a few thousand kroner from an employment relationship alongside his studies:
If the student gets a job in the public sector, and keeps the pension capital certificate, a significant part of the money could be eaten up by an annual administrationfee that comes in addition to a management fee of a percentage of the capital.
However, if the student chooses NITO's agreement with Nordea Life, there are no administrationfees in addition to lower management fees, and the money can be worth several times more when the student retires 40 years later.
Therefore, early choice can yield much more later
Aarbakke asks you to take a check and take action now. The current scheme has lasted for about 20 years, while an entire working life usually lasts for 40 years. "The importance of management costs grows over time, the lower the costs and fees, the more money you will have to spend when you retire," says Aarbakke.
He can understand that many people think pensions are complicated, but he believes that it doesn't really have to be that difficult.
"What you can control is price. Whether one supplier is better than another at creating extra returns is less clear. But the difference in costs is quite real," says Aarbakke.
He recommends that you check what kind of scheme you have today.
Here's how to do it
1) Check your pension
Go to the website norskpensjon.no. Here you log in with Bank-ID, and you can see how much the costs are for your pension account.
Ifyou work in the private sector or have you ever had a job with an employer in the private sector after 2006, you have earned a pension during the time you have worked.
All earned definedcontribution pension (including previously earned "pension capital certificates") is collected with your employer's pension provider in what is called a separate pension account, but this only applies if you are employed by an employer in the private sector with a defined contribution pension.
2) Check if you can get a cheaper pension account
The solution you have today for your pension account is what the employer has managed to negotiate in terms of arrangement with a pension manager (bank/financial institution).
If you work in a company with very few employees, there is a high probability that you will pay relatively high fees and management costs. You should see if you can get a cheaper solution.
Find the compensation rate: This is the cost contribution you will receive from your employer if you transfer your pension money.
" The higher the compensation rate, the wiser it is to move," says Moen.
If you are a member of a professional organisation such as NITO, you will be able to save a lot by choosing the solution offered through Nordea, which is NITO's partner in banking and pensions. When NITO, with its well over 100,000 members, negotiates in the market, you get very low management costs and more pension for your money.
3) Consider choosing NITO's pension account
If the compensation rate is higher than what you can get from Nordea, you can easily chooseto switch.
You click on Move your pension on Nordea's website.
Nordea will then take care of the rest for you and ensure that you earn your pension at a reasonable price. You can contact Nordea's advisers at any time for more information, or you can change your pension provider at any time.
It may be a good idea to check Finansportalen's price list and see which scheme you can get under and get an insight into the prices in the market.